IA-02
Client Acceptance and Engagement Kit
Accept the client and contract with confidence: acceptance assessment, conflict check, engagement letter, independence and fees.
Inside the kit
What this kit solves
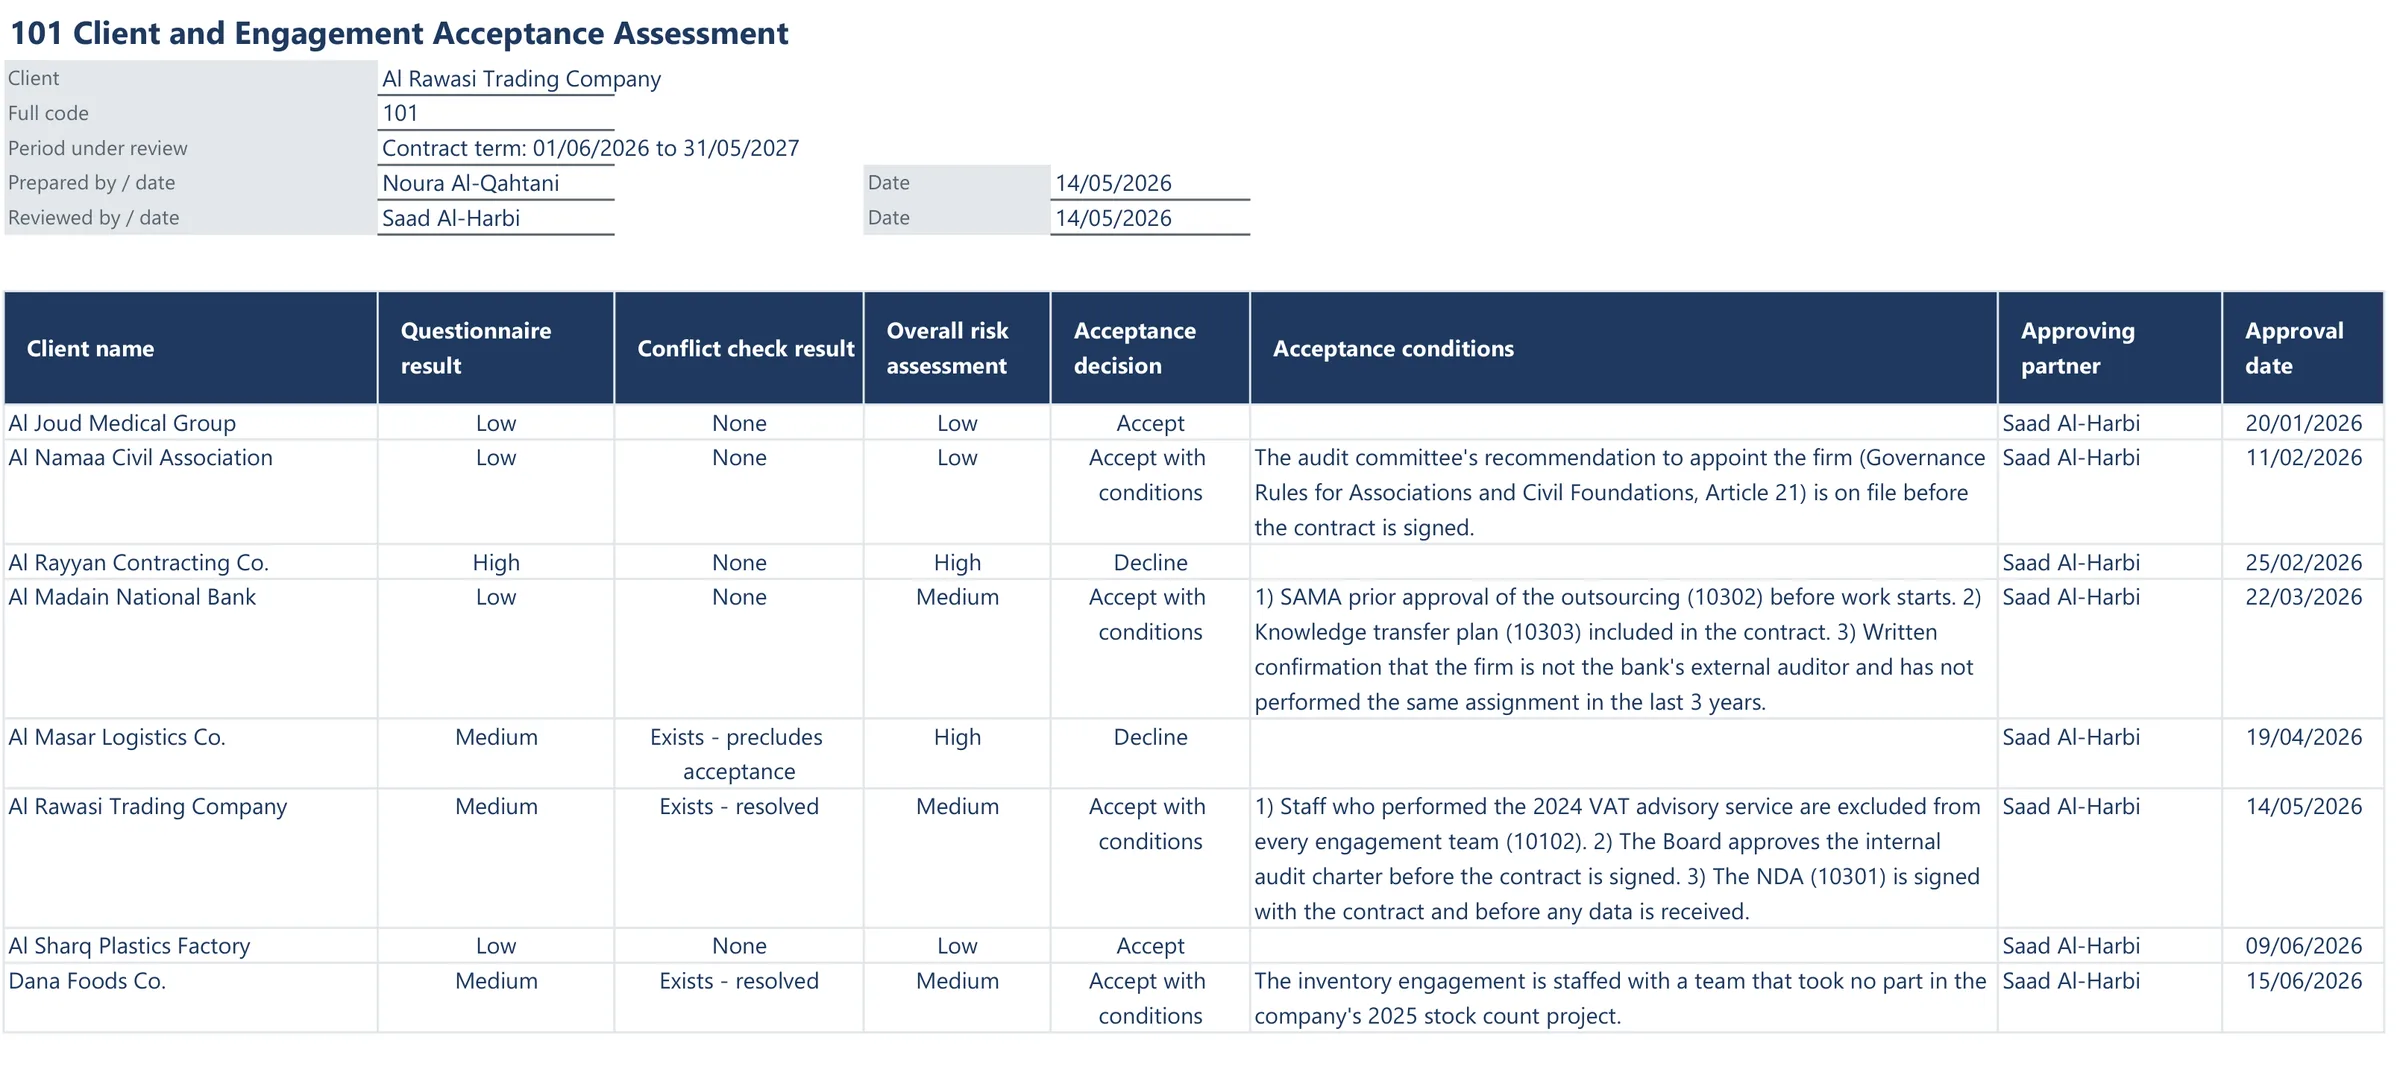
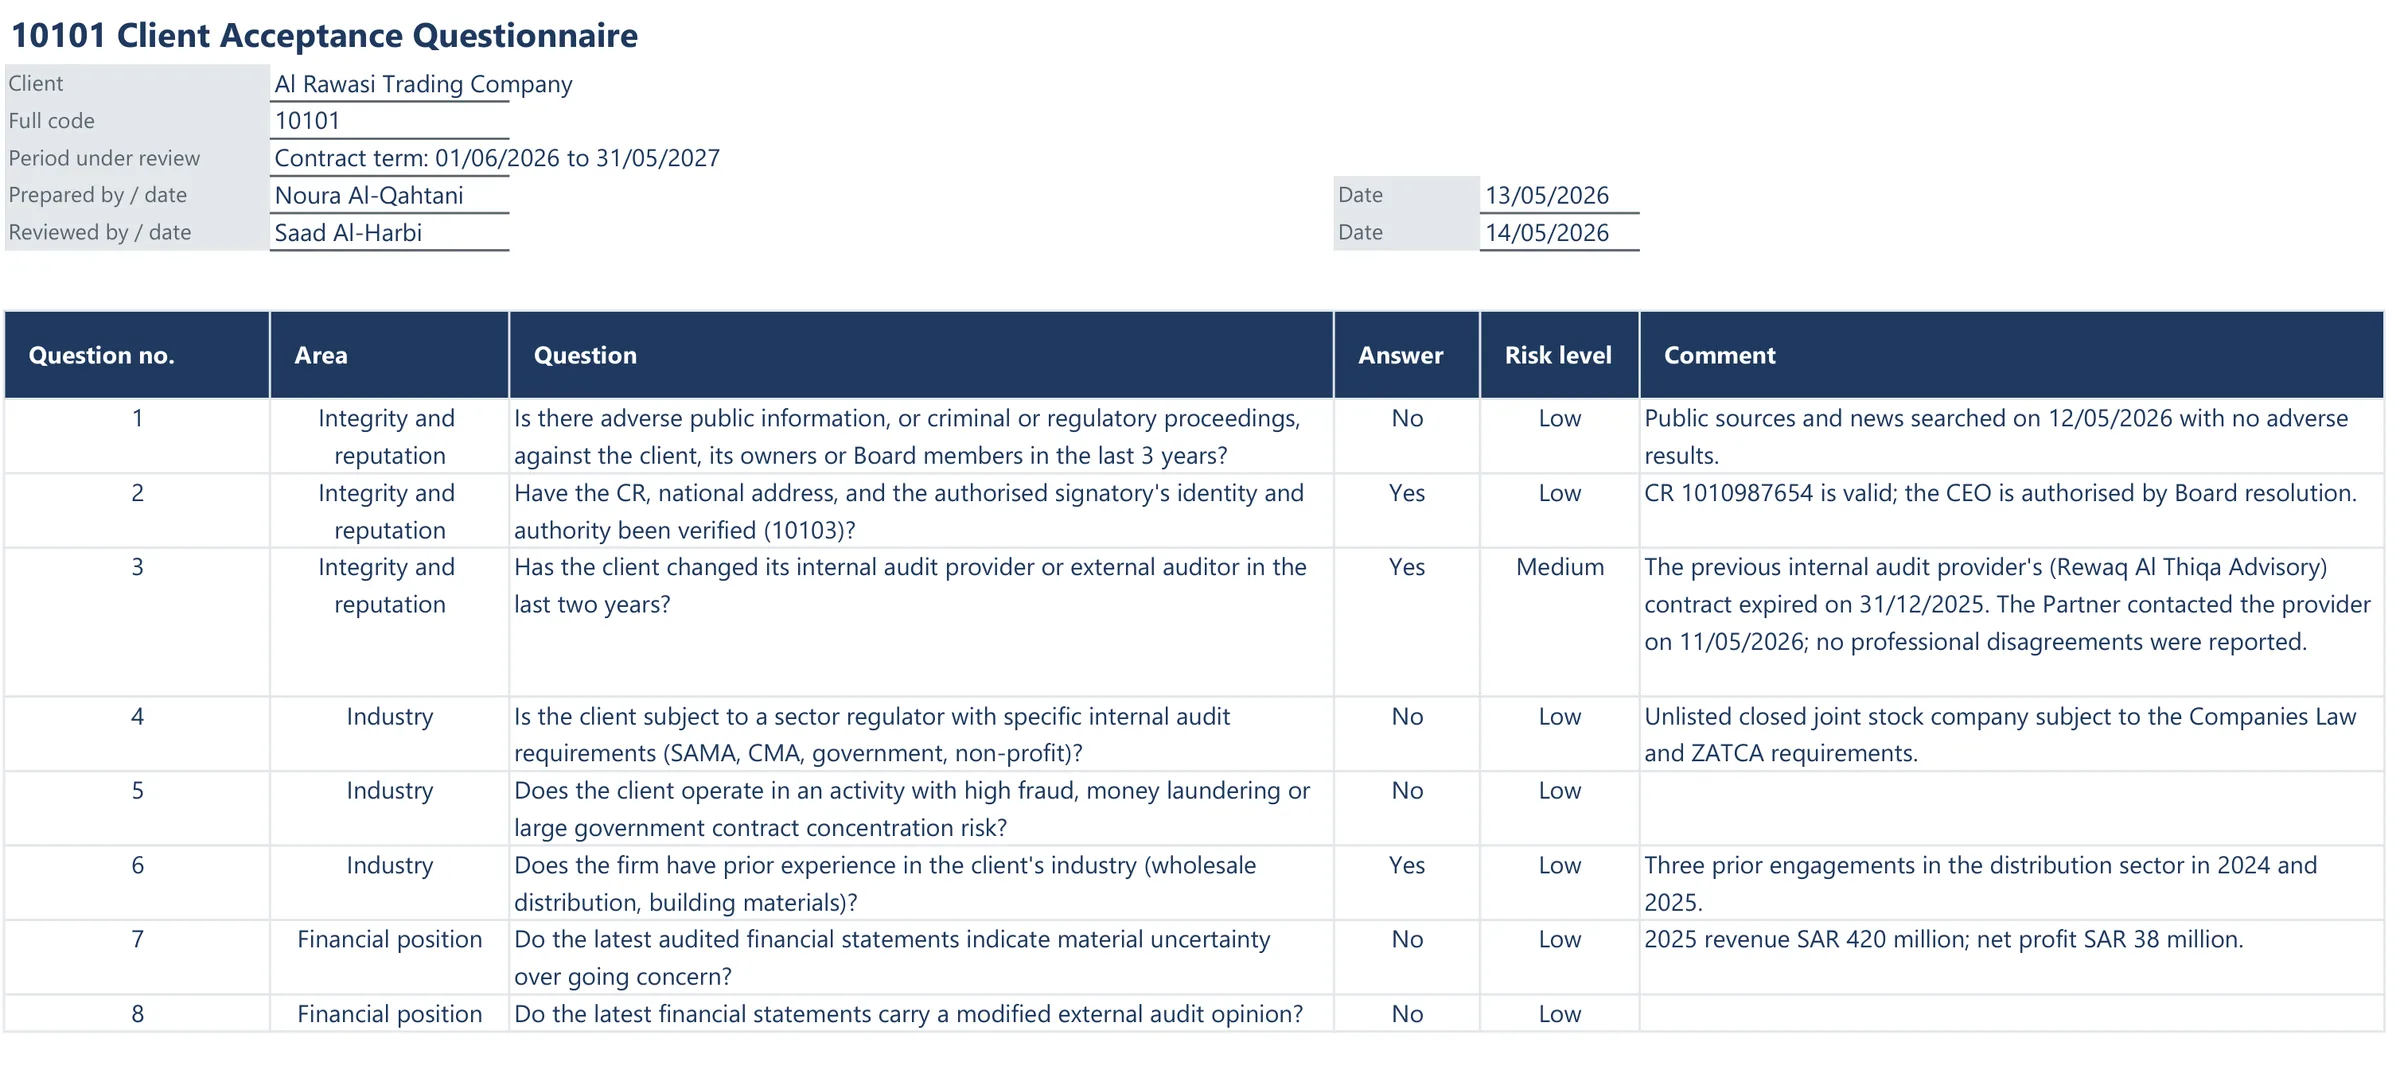
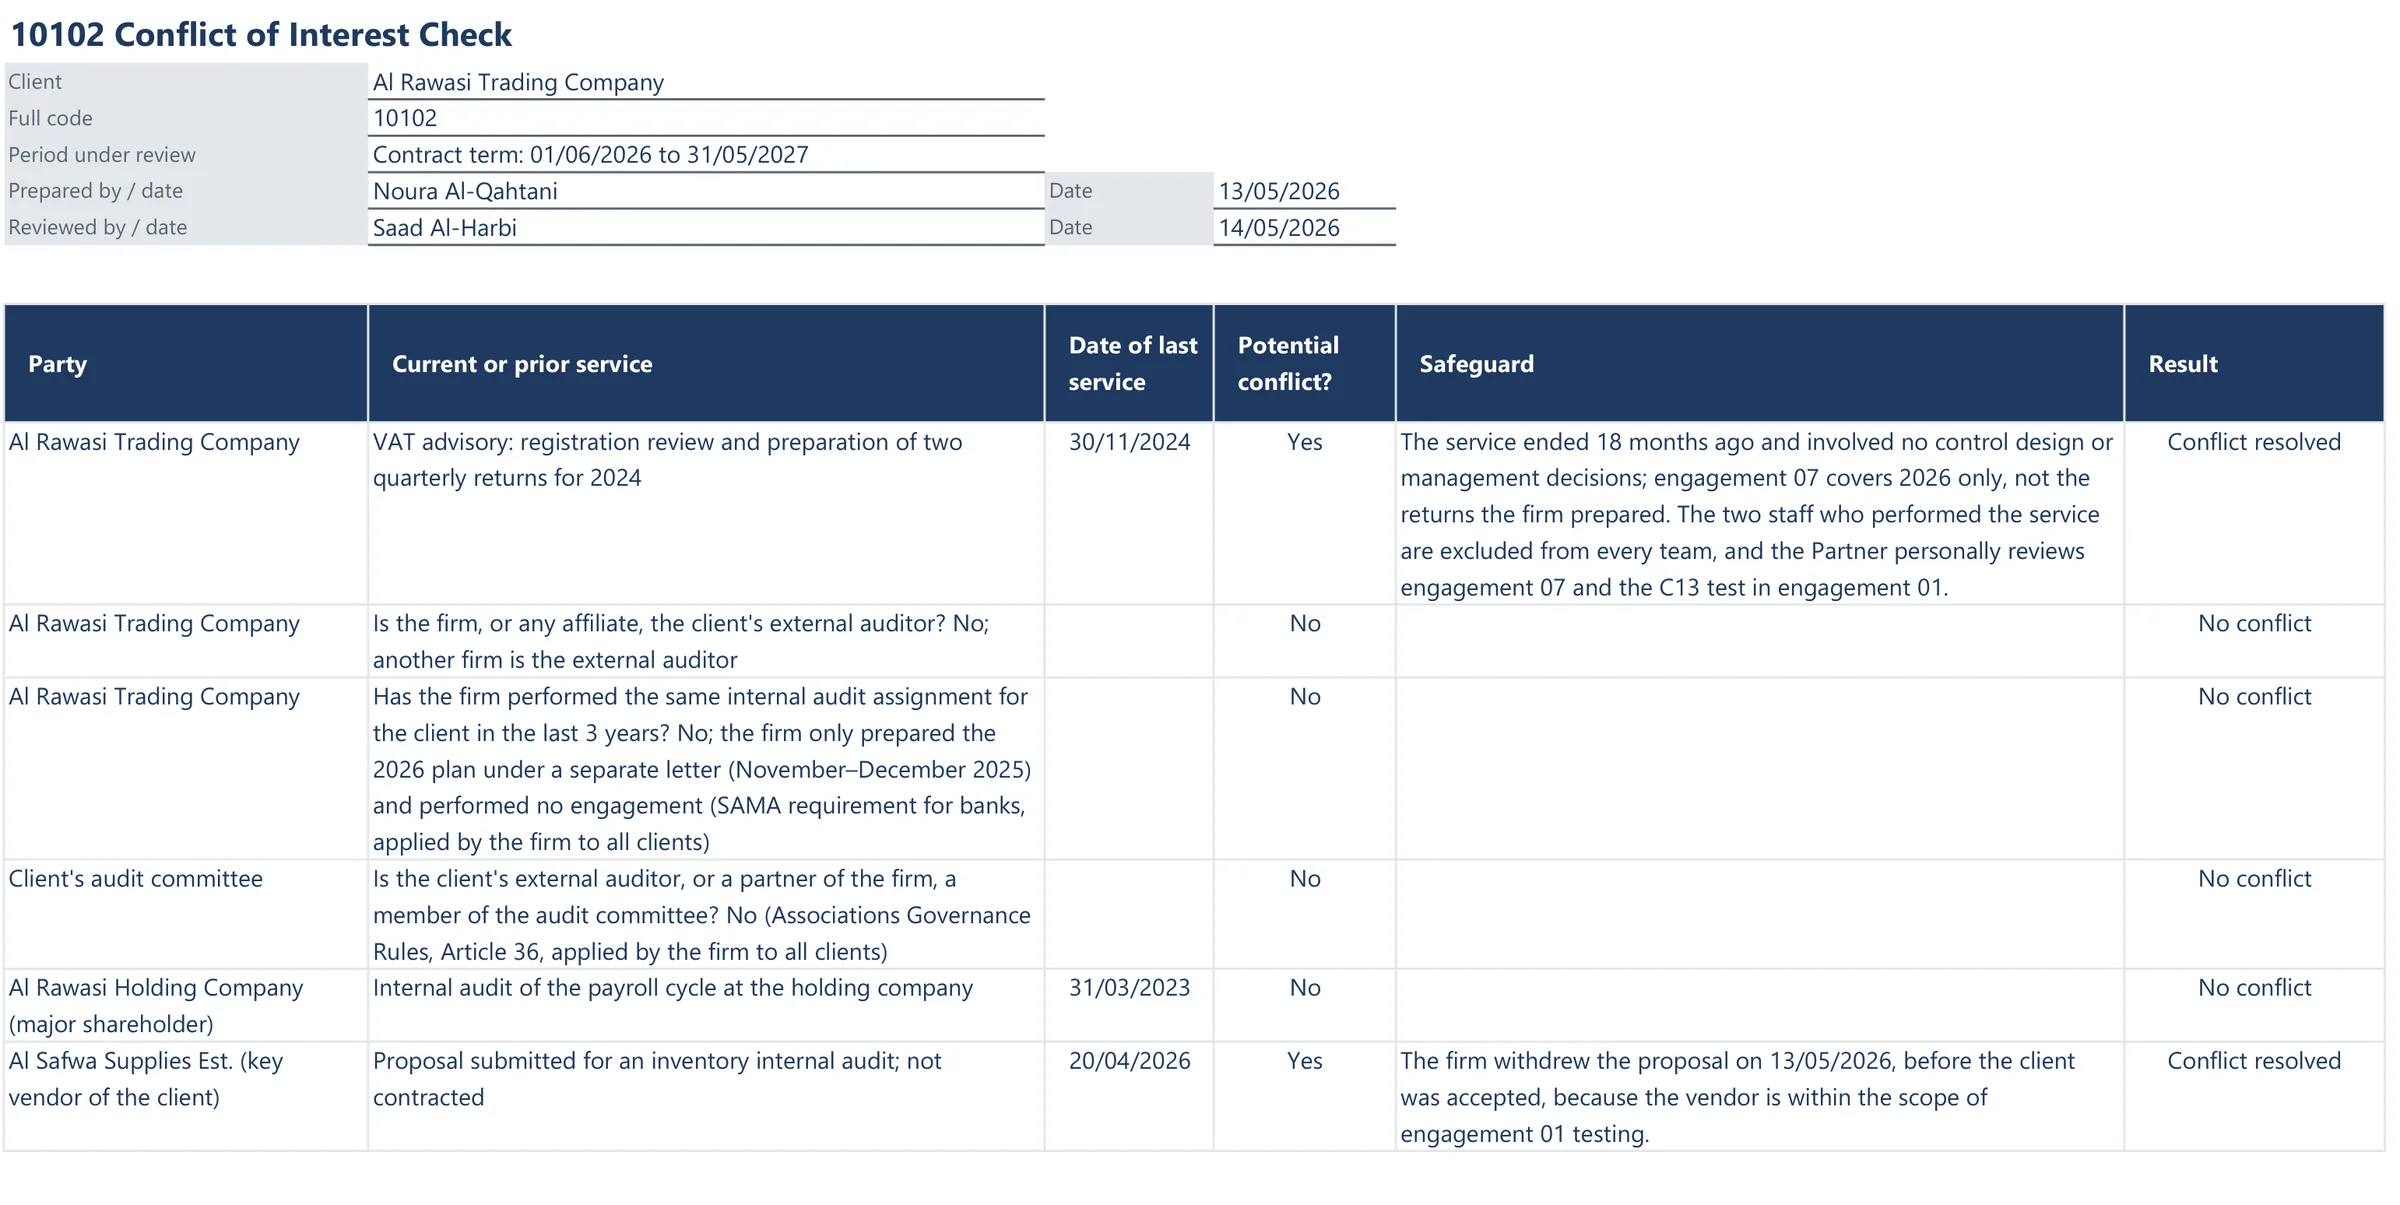
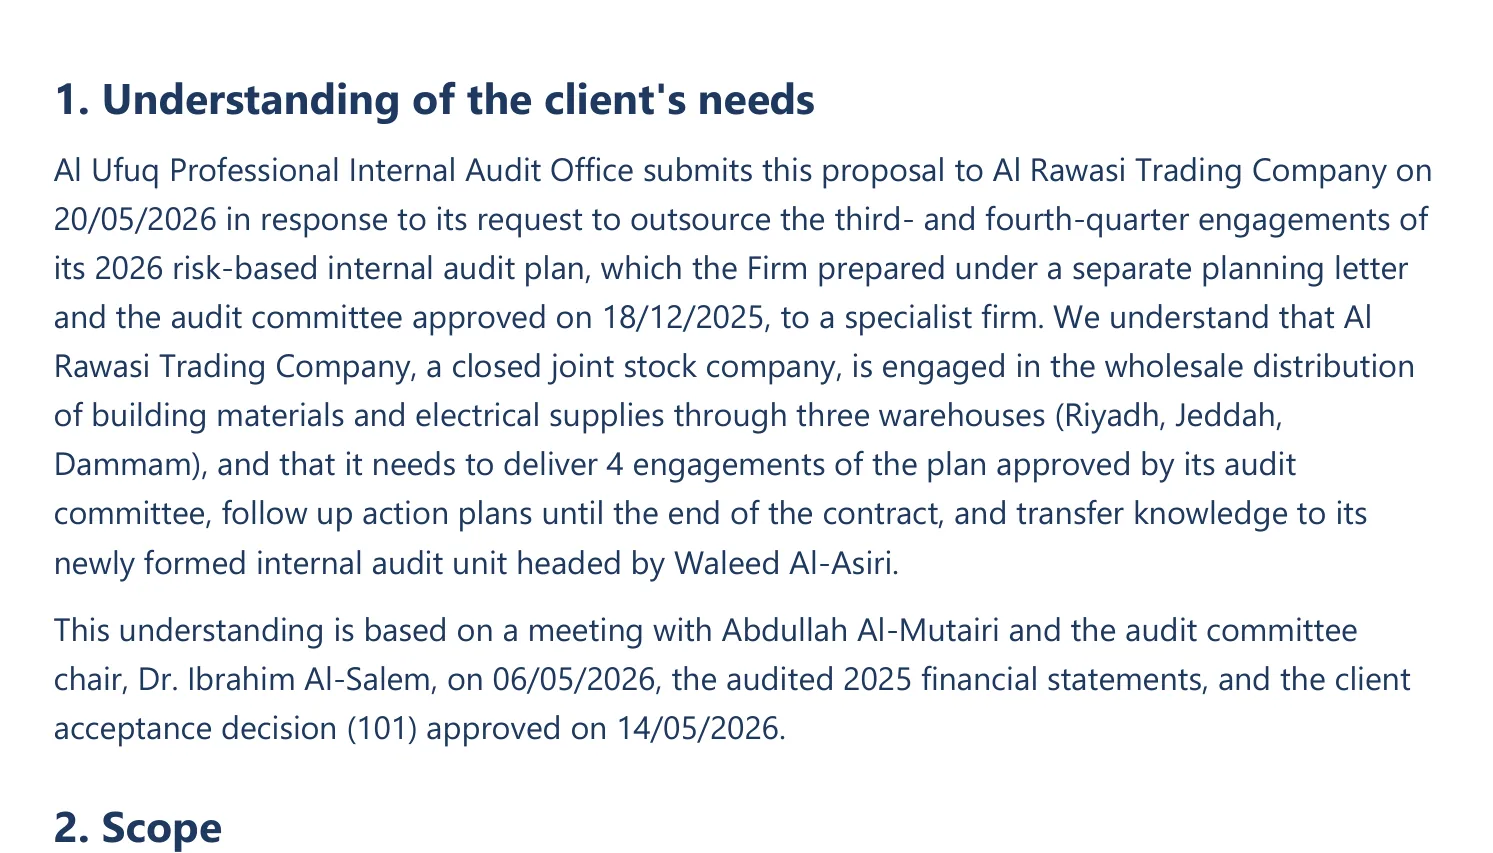
Accepting a client without a documented assessment, or starting work before the contract and independence declarations are signed, leaves the firm exposed at quality review. This kit covers acceptance and contracting in full: the acceptance assessment (101) with questionnaire (10101) and conflict of interest check (10102), the proposal (102), engagement letter (103) and NDA (10301), independence and objectivity declarations (104), team composition (105), the scope change log (106) and fee tracking (107). Slots hold client documents and signed copies, and each template includes a filled example. The templates include notes on SAMA outsourcing rules for local banks, NCNP rules for associations, and the Council of Ministers regulation for government entities.
What your file holds afterwards
- A documented acceptance assessment (101) with the questionnaire (10101) and conflict of interest check (10102)
- A technical and financial proposal (102), engagement letter (103) and NDA (10301)
- An independence and objectivity declaration form (104), with slots for signed partner and team declarations (10401–10403)
- Team roles and hours (105), a scope change log (106) and invoicing and collection tracking (107)
- Banks only: a slot for evidence of SAMA prior approval of outsourcing (10302) and a knowledge transfer plan (10303)
How to use it
- Assess acceptance in 101 with questionnaire 10101 and conflict check 10102, and file due diligence documents in 10103.
- Prepare the proposal in 102, then the engagement letter in 103 and the NDA in 10301.
- Collect independence declarations under 104 and set up the team in 105 before work starts.
- Log every scope change in 106 and track invoices and collections in 107.
Who it is for
Audit firms accepting a new client or engagement, from the initial assessment through contract signature and fee tracking.
What is in the kit
| Code | Paper | Format | What you get | Reference |
|---|---|---|---|---|
| 101 | Client and Engagement Acceptance AssessmentReference: ISQM 1 | Excel | Template + worked exampleTemplate + example | ISQM 1 |
| 10101 | Client Acceptance QuestionnaireReference: ISQM 1 | Excel | Template + worked exampleTemplate + example | ISQM 1 |
| 10102 | Conflict of Interest CheckReference: 2.1, 2.2 | Excel | Template + worked exampleTemplate + example | 2.1, 2.2 |
| 10103 | Client Due Diligence DocumentsReference: ISQM 1 | — | Slot for a client documentClient document | ISQM 1 |
| 102 | Technical and Financial ProposalReference: Administrative | Word | Template + worked exampleTemplate + example | Administrative |
| 103 | Engagement Letter / Signed ContractReference: 6.1 | Word | Template + worked exampleTemplate + example | 6.1 |
| 10301 | Non-Disclosure Agreement (NDA)Reference: 5.2 | Word | Template + worked exampleTemplate + example | 5.2 |
| 10302 | Evidence of SAMA Prior Approval for Outsourcing (Banks Only)Reference: SAMA Internal Audit Principles | — | Slot for a client documentClient document | SAMA Internal Audit Principles |
| 10303 | Knowledge Transfer Plan for Client Staff (Banks Only)Reference: SAMA Internal Audit Principles | Word | Template + worked exampleTemplate + example | SAMA Internal Audit Principles |
| 104 | Independence and Objectivity DeclarationsReference: 2.1, 2.3 | Word | Template + worked exampleTemplate + example | 2.1, 2.3 |
| 10401 | Partner and Engagement Manager Independence DeclarationReference: 2.1 | — | Slot for a signed copy of another templateSigned copy | 2.1 |
| 10402 | Team Member Independence DeclarationsReference: 2.1 | — | Slot for a signed copy of another templateSigned copy | 2.1 |
| 10403 | Annual Independence DeclarationReference: 2.1, 2.3 | — | Slot for a signed copy of another templateSigned copy | 2.1, 2.3 |
| 105 | Engagement Team and ResponsibilitiesReference: 13.5 | Excel | Template + worked exampleTemplate + example | 13.5 |
| 10501 | Team CVs and Professional CertificatesReference: 3.1 | — | Slot for a client documentClient document | 3.1 |
| 106 | Scope and Contract Change Log (Change Orders)Reference: 13.3 | Excel | Template + worked exampleTemplate + example | 13.3 |
| 10601 | Signed Contract AddendaReference: Administrative | — | Slot for a signed copy of another templateSigned copy | Administrative |
| 107 | Invoicing and Fee TrackingReference: Administrative | Excel | Template + worked exampleTemplate + example | Administrative |
Every kit also includes a user guide (PDF and PowerPoint) and the licence terms, in Arabic and English.
IIA Global Internal Audit Standards (2024) references, with ISQM 1 and SAMA principles where they apply, as given in the guide. References are for cross-referencing and do not imply IIA endorsement.
Where it sits in the audit cycle
- 000File AdministrationIA-01
- 100Acceptance, Engagement and AdministrationIA-02
- 200Permanent and Annual FileIA-03IA-04
- 300Engagement PlanningIA-05IA-08
- 400Process Understanding and Control AssessmentIA-06IA-08
- 500Testing and FieldworkIA-07IA-08
- 600FindingsIA-09
- 700Reporting and Follow-upIA-09IA-10
- 800Advisory EngagementsReplaces 400–700 on advisory engagementsIA-11
- 900Quality Review and File ClosureIA-12
Sector notes inside the templates
- Local banks — Saudi Central Bank (SAMA)
Outsourcing limited to specialised assignments; requires SAMA prior approval, a non-disclosure agreement and knowledge transfer to staff; the provider may not be the external auditor or be re-engaged for the same assignment within 3 years (Internal Audit Principles for Local Banks (effective 1 January 2022)) - Associations and civil foundations — National Center for Non-Profit Sector Development
The committee reviews internal control and recommends the appointment of the internal auditor (Governance Rules for Associations and Civil Foundations (Umm Al-Qura, 2023) — Article 21) - Associations and civil foundations — National Center for Non-Profit Sector Development
The external auditor may not be a member of the internal audit committee (Governance Rules for Associations and Civil Foundations (Umm Al-Qura, 2023) — Article 36) - Government entities — Council of Ministers
General standards: full independence, impartiality, confidentiality and due professional care (Unified Regulation for Internal Audit Units in Government Agencies and Public Institutions (Resolution No. 129 dated 6/4/1428H))
The affected templates carry a short line for each requirement with its reference. Check the official text of each reference before relying on it; regulations change.